


Navigating Life Insurance and Divorce: A Complete Guide
Underwritten by United of Omaha Life Insurance Company


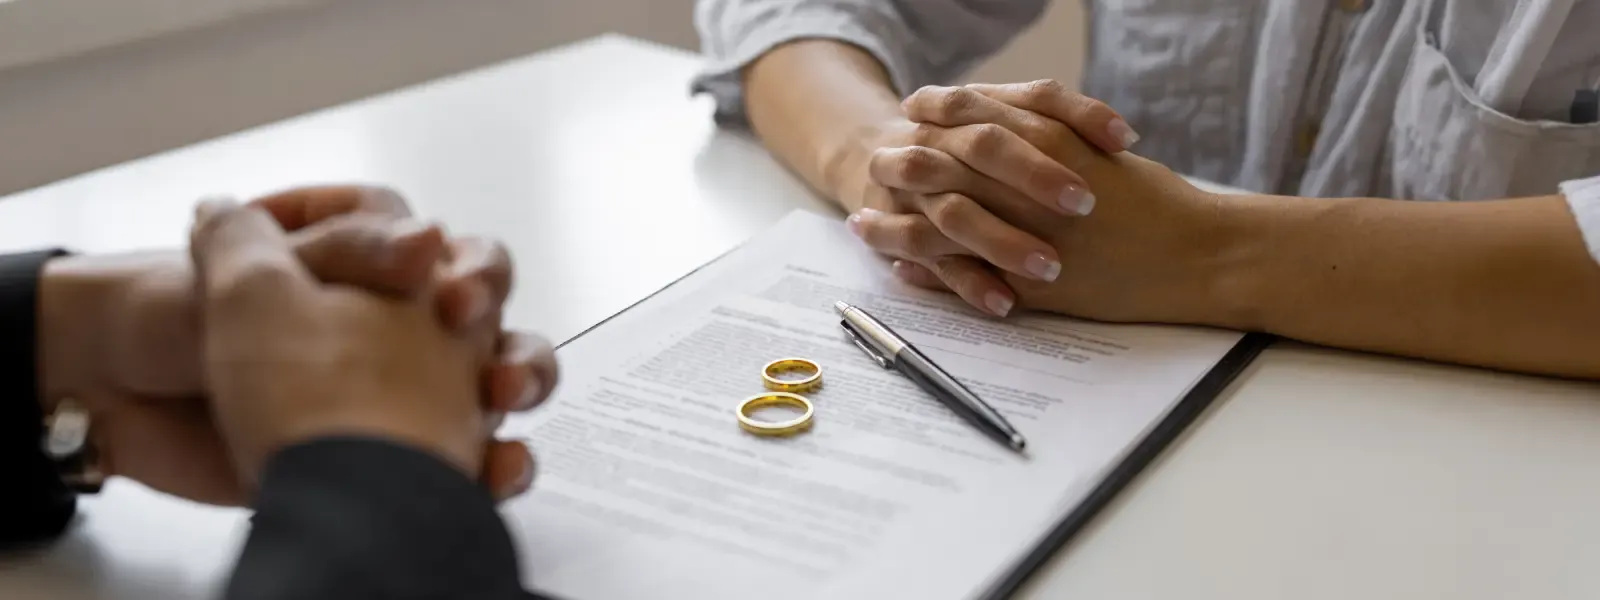
Life insurance policies can require review and updating during a divorce. Beneficiaries may need to be changed, and a policy’s cash value may be considered a marital asset to be divided. A court may even order a policy to ensure alimony or child support obligations are met. Updating your policy to reflect your new situation helps protect you and your beneficiaries.
Divorce rates are increasing, especially among those age 65 and older.¹ So, it’s natural to be concerned about what will happen if you’re no longer with your partner.
During a divorce, many people focus on the emotional impact and may overlook some of the legal aspects. One area people may not consider is how the process can affect existing life insurance plans.
There are steps you can take to help protect your life insurance policy and yourself during a divorce. Keep reading to learn more about life insurance and divorce.
In this article:
What happens to life insurance during a divorce?
Life insurance beneficiary rules after divorce
What steps should you take during a divorce?
Types of life insurance after divorce
What happens to life insurance during a divorce?
Your policy may change during the divorce court process, but changes are not automatic. You’ll need to make them yourself. Confirm that your coverage offers the right protection now that your circumstances have changed. You may also consider changing the beneficiaries if you no longer wish for your ex-partner to receive a death benefit.
If you have a joint policy, some insurers may allow you to turn it into two separate policies. In this case, two options may be available:
One partner takes the entire policy, and the other partner buys a new life insurance policy.
You cancel the policy and apply for a new policy that suits your circumstances.
Life insurance beneficiary rules after divorce
Life insurance policies will likely come up during the divorce court process, typically regarding the beneficiaries and payout amount. Common considerations include:
If a spouse must pay alimony or child support to an ex-partner, they may be asked to retain the ex-partner as the beneficiary.
You may need to purchase a new policy that would pay an amount to your ex-partner if you pass away.
Consult with your lawyer to understand the beneficiary rules. They may be able to advise you on how to handle your policy through the divorce settlement.
What steps should you take during a divorce?
If you have a policy in place and are undergoing a divorce, make any necessary updates to help ensure it serves its intended purpose. Consider the following steps:
-
Update your policy beneficiaries
Spouses often name each other as the primary beneficiary of their insurance policies. If you no longer wish for your partner to benefit from your insurance, you may be allowed to remove them from the list.
Some states automatically remove ex-partners from a policy, as allowed by the Uniform Probate Code.² In other states, you’ll need to contact your insurance company to make the change.
In either case, you’ll need to name a new beneficiary. Keep in mind that naming a minor can lead to delays in receiving a benefit.
If you die before updating your beneficiary, the listed beneficiary will receive the benefit. No one can change the beneficiary after the policyholder passes away. Therefore, if you don’t wish for your ex-partner to receive the benefit, remove them from the beneficiary list as soon as possible.
You may also have named an irrevocable beneficiary when you applied. An irrevocable beneficiary generally cannot be changed without the beneficiary’s consent, even during a divorce.
-
Help protect your children
As a newly single parent, you can buy life insurance coverage to help protect your children. A new policy after a divorce may provide financial support to help sustain them until they are adults.
Minors generally cannot take ownership of a policy. If you pass away while your children are young, a court may appoint someone to manage the funds on their behalf. This process can be expensive and may delay access to the money.
You may help avoid a delay by establishing a living trust and naming it as your life insurance beneficiary. The adult trustee you choose will manage the funds and distribute them to your children according to the trust’s instructions.
-
Determine the marital portion of your cash value
Cash value is the amount that accumulates in a life insurance policy over time. It applies to certain permanent policies, including whole life and universal life insurance. Term life insurance does not accumulate cash value.
When the policyholder pays a premium, the insurer may put a portion of the money into a fund that can grow over time. You may be able to access this money while your policy is active, but doing so may reduce the death benefit.
Your cash value is part of your net worth. When listing your life insurance policy during divorce proceedings, include its cash value, which may be divided with other marital assets.
Court-ordered life insurance
Sometimes, family courts may order life insurance to support alimony payments or secure child support.³ This is known as court-ordered insurance and is mandated by a judge, typically when one spouse has a significantly larger income than the other or when the spouses have children.
Court-ordered life insurance usually protects alimony and helps provide child support payments if the responsible spouse passes away. The parent without custody may be required to make premium payments, and the court may allow the custodial parent to own the policy, depending on the circumstances.
If that happens, the insurance company may notify the policy owner of changes to the policy or allow them to pay the premium if the other parent does not.
Types of life insurance after divorce
If you’re thinking about purchasing a new life insurance policy after your divorce, you may want to consider these options:
Whole life insurance Whole life insurance is a type of permanent life insurance that can offer lifelong protection as long as required premiums are paid. It usually includes cash value that may be accessed for financial needs while you are alive.
Final expense insurance. Sometimes called funeral or burial insurance, it generally offers a smaller death benefit. It can help cover funeral expenses, medical bills and legal costs.
Term life insurance Term life insurance offers coverage for a specific period. If you die during that period while the policy is active, your beneficiaries will receive the policy’s death benefit.
Universal life insurance. This type of policy may allow you to adjust premiums and death benefits as your circumstances change, subject to policy terms.
Take control of your life insurance
Every divorce is unique. How your life insurance may change depends on the terms of your divorce agreement. Even when the court does not mandate life insurance as part of the settlement, it can be helpful to review your coverage.
Update your beneficiaries and contact information, and make sure the policy provides enough coverage for your changed circumstances. A new policy may provide greater independence and clarity.
A new policy tailored to your current needs may help restore peace of mind. Ready to help protect your dependents with whole life insurance?
Frequently asked questions about life insurance and divorce
1. How much life insurance should you have after a divorce?
The right amount depends on your new situation. After updating your beneficiaries, you may need to adjust your coverage based on their needs. Speak with an insurance agent or producer about the best way forward.
2. Can I name my child as a beneficiary after the divorce?
Yes, but doing so may create complications if the child is a minor. State rules vary, and a court-appointed guardian or other arrangement may be required to manage the benefit. Consider working with a financial or legal professional before naming a minor as a beneficiary.
3. Is life insurance a marital asset?
It depends on the type of policy. Permanent policies, such as whole life or universal life insurance, may feature cash value that grows over time. That cash value may be considered a marital asset because policyholders may be able to borrow against it or surrender the policy for cash.
Sources
1. National Library of Medicine, The Graying of Divorce: A Half Century of Change, April 2022
2. Cornell Law School, Uniform Probate Code, April 2025
3. Cornell Law School, Child Support, July 2022
Subscribe for the latest articles, financial calculators and resources
Suggested content for you in Life Insurance
-
Funeral Crowdfunding
-
Is Life Insurance Part of Your Financial Portfolio?
-
Funeral Fundraisers: What’s Involved and Is It Worth the Risk?
-
5 Mistakes to Avoid When Shopping for Life Insurance
-
Life Insurance Facts: Debunking the Myths
-
How Does Life Insurance Work?
-
Life Insurance Awareness Month
-
What to Look for in a Life Insurance Policy
-
How to Create a Will: A Step-by-Step Guide
-
5 Qualifying Life Events: Reasons to Update Life Insurance Coverage
Explore other topics
Eating Well
Is Keto Diet Safe for Older Adults?Medicare Parts & Plans
Medicare Supplement Plan G vs. Plan N: Which One’s Best for You?Traveling in Retirement
Top 5 Cities for Seniors to Retire All Categories
 Medicare
 Retirement Planning
 Business Resources
 Life Insurance
 Financial Planning
 Health & Well-Being
 Travel & Living