


5 Mistakes to Avoid When Shopping for Life Insurance
Underwritten by United of Omaha Life Insurance Company


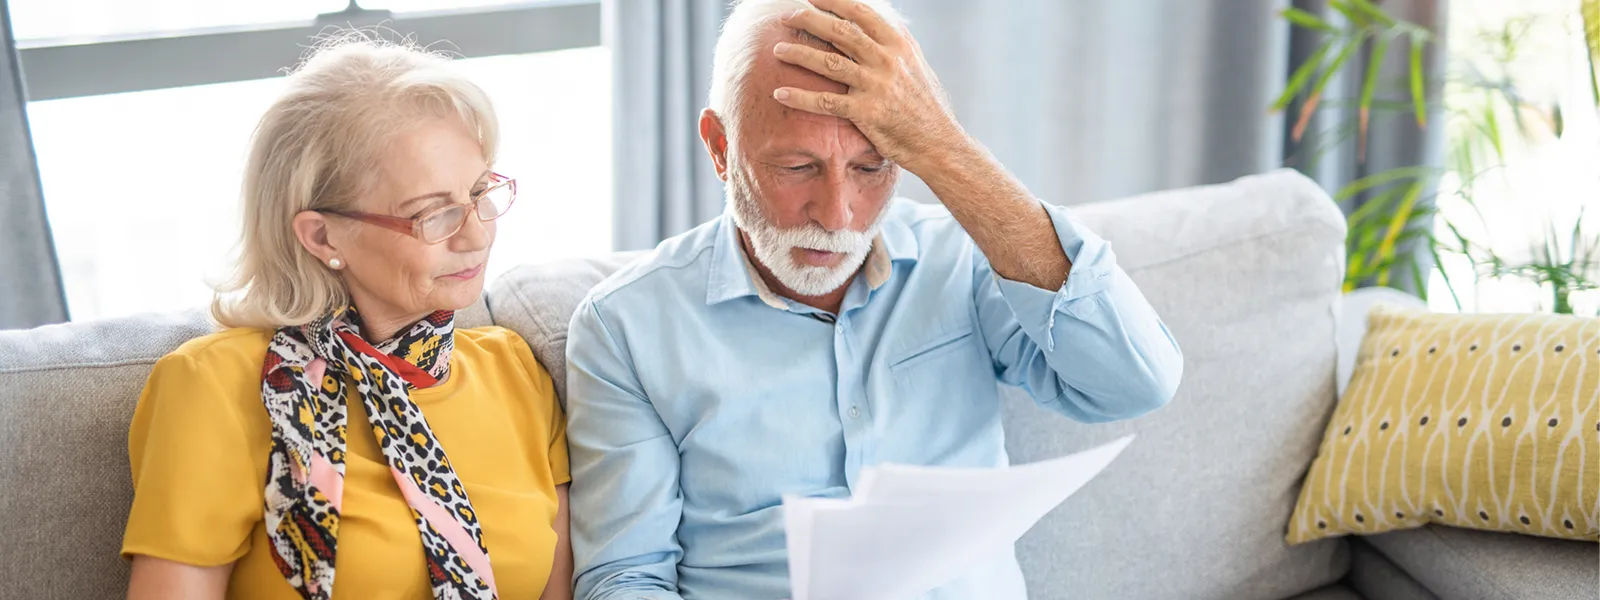
Many people make avoidable life insurance mistakes, such as underinsuring, delaying coverage, or choosing price over protection. Applying early, choosing adequate coverage, and giving accurate information helps ensure your loved ones are properly protected.
In this article:
#1: Buying too little coverage
#3: Choosing a plan based on price rather than coverage
#4: Failing to review and update your policy
#5: Providing incorrect information
Avoid life insurance shopping mistakes and get the right policy
Help protect your family’s future by avoiding life insurance mistakes
Frequently asked questions (FAQs)
Life insurance may feel complex for many people. But when days may become unsteady for a family dealing with a loved one’s unexpected death, life insurance can be a guide for the path forward. Insurance terms may be unfamiliar, and policy wording and features might be difficult to understand. Too many options may make it confusing to get the right policy with the right benefits. The right life insurance can help your loved ones when they need it most.
To help ensure you're getting the coverage you need, let's look at five common mistakes to avoid when shopping for life insurance, and what you can do instead.
#1: Buying too little coverage
While some life insurance coverage can be better than none, an insufficient life insurance payout may not go far enough to help protect your family.
According to the 2025 Insurance Barometer Study, 40% of American adults reported needing more life insurance than they currently have. Gen Z and Hispanic adults were less likely than other demographics to have life insurance policies.1
A sufficient death benefit can help your family at a time of need, including with:
Burial and final expenses: Pay for funeral, burial, cremation, or other end-of-life expenses to help alleviate some financial strain.
Daily expenses: Provide funds for basic needs, such as housing, groceries, utilities, and childcare.
Financial management: Offer flexibility to help pay for debts, including loans, credit cards, and other debts, while reducing the need to take on additional debts.
Future goals: Help fund long-term goals like higher education for your children and financial support for your spouse during retirement.
Lessens emotional stress: Give your family members some peace of mind in knowing you prearranged for financial stability.
Business stability: Allows businesses to continue uninterrupted by helping to provide the necessary resources to keep operations running.
#2: Waiting too long
Young adulthood can often be a life stage filled with hope and optimism. For many young adults, life insurance isn’t a top priority when they are young and healthy, and it may be hard to foresee a time when they’d need to rely on life insurance. Yet, age can affect life insurance rates.
Life is unpredictable at every age. Planning ahead can be an important way to help protect the people you love. Research from Boston University highlights a growing awareness that adults aged 25 to 44 may face more risks today than in the past, largely driven by accidents and health-related challenges. Understanding these realities empowers people to turn to life insurance to help provide a more secure future for their loved ones.2
Younger individuals may have assets or dependents that need the temporary or permanent protection that life insurance can easily provide. If you wait too long to purchase life insurance, it may be too late to benefit your family. Some considerations to not delay buying life insurance might include:
-
Locking in favorable rates:
You may get better rates when you're young and healthy.
-
Insurability:
Your health may decline as you age, which might make it difficult to get life insurance.
-
Cash value growth:
You’ll have more years for the cash value of a permanent life insurance policy to grow. (Cash value may decrease if it is used through withdrawals or loans.)
Life insurance rates go up with every year you age. The sooner you buy a policy, the more budget-friendly it can be. If you don’t buy a policy when you are young, you can still get life insurance past age 65. Guaranteed whole life insurance policies are available to individuals ages 45 to 85 (ages 50 to 75 in New York State) with no medical exam.
#3: Choosing a plan based on price rather than coverage
If budgeting is a concern, you’ll want to understand the differences between term vs. whole life insurance. Both types of policies offer fixed premiums. Understanding that the right life insurance policy prioritizes meaningful protection over small monthly savings may give your family a sense of security, and there are a variety of policies to get the exact coverage you need. Riders can help further customize your coverage.
Consider the following issues to avoid life insurance mistakes based on pricing:
Adequate protection
Less expensive options may leave your family with coverage gaps, potentially causing financial strain.
Long-term financial security
The best protection accounts for inflation, health costs, and childcare, and helps protect your family’s standard of living for years to come.
Value over cost
The right policy delivers an adequate death benefit, customizable riders, and budget-friendly premiums.
Features
Riders, whether included or offered at an additional cost, may provide additional benefits, including living benefits, disability benefits, conversion privileges, and more.
Life changes
A common life insurance mistake is failing to account for life changes such as marriage, homeownership, or entrepreneurial ventures, and buying more insurance later generally comes at a higher cost.
Group vs. individual policies
Employer-based group policies may be cheaper, but you may not be able to continue them after leaving your employer, and an individual policy may have a higher cost.
#4: Failing to review and update your policy
Changes like getting married, having children, buying a home, or starting a business can affect the amount of life insurance coverage you need. Reviewing and updating your life insurance needs can help ensure coverage during times such as:
-
Family changes
Marriage, divorce, a home purchase, career transitions, and other family changes can dramatically alter your life and your life insurance needs.
-
Income and expense changes
New financial obligations, salary increases, and job changes may increase or reduce your life insurance coverage needs.
-
Beneficiary changes
Relationships can evolve as we go through life. Updating your beneficiaries ensures your funds reach the intended recipients.
-
Debt changes
You may take on a mortgage, student loans, an auto loan, credit card debt, or some other debt. You may need more life insurance to cover the debts.
Review your policy in full, including the fine print, to make sure you’ve covered the most important bases. Pay special attention to the policy exclusions to understand the circumstances where coverage doesn’t apply. Make it a practice to review your policy at least yearly, so you can make necessary adjustments to your life insurance needs right away. You can change your beneficiary at any time.
#5: Providing incorrect information
Providing correct information helps prevent problems and can streamline the approval process. Here are some of the reasons it’s critical to be honest and forthcoming in your answers to life insurance application questions:
Prevent policy rescission. Misstatements discovered during the contestability period can void your policy, even if your mistake was unintentional.
Prevent claim denials. Inaccurate or incomplete information can delay a claim or deny benefits, leaving your family without coverage when they need it most.
Help protect beneficiaries. Accuracy ensures that your beneficiaries will receive a payout and nothing is left to chance.
Ensure proper underwriting and pricing. Accurate information allows underwriters to evaluate your risk profile and assign the proper rate class, which may even be in your favor.
Considering that life insurance policies are legally binding contracts, it’s essential to complete your application accurately to ensure that it’s valid and enforceable.
Avoid life insurance shopping mistakes and get the right policy
Your life insurance needs are different from everyone else's. By understanding the different types of life insurance, you can better choose a policy that will serve your family now and in the future. Get quotes and compare features to help you make an informed decision. The right policy should align your coverage amounts, terms, and benefits with your life goals.
Here are some quick reminders to consider when shopping for life insurance:
Align coverage with current and future goals.
Act sooner rather than later.
Favor protection over pricing.
Review your policy and update it annually.
Complete your application honestly and accurately.
Check the insurance company’s financial strength ratings.
Consider riders or add-ons to enhance your coverage.
Help protect your family’s future by avoiding life insurance mistakes
Take the time to review the coverage and terms, and compare them with your long-term needs. By understanding your options and avoiding common pitfalls, you can feel more confident that the coverage you choose will support the people who rely on you.
Life insurance decisions can be challenging. United of Omaha Life Insurance Company, a Mutual of Omaha company, has served customers for over a century by offering a variety of life insurance policies to meet every need. Get professional guidance about the basics of life insurance from our insurance agents or producers to help inform your decision.
Frequently asked questions (FAQs)
1. How do I determine how much life insurance coverage I need?
Project how much money your loved ones would need if you were gone. Consider income needs, outstanding debts, and everyday living needs. A life insurance calculator is an easy way to learn how much life insurance you need.
2. How can I ensure I’m not overpaying for life insurance?
The same policies from different insurance companies may vary in price. Get multiple quotes and compare the features and prices.
3. Why is it important to compare life insurance policies?
By exploring multiple options, you can find policies with the right features, coverage amounts, and value. Side-by-side comparisons will help you identify which policy will work best for your family.
Subscribe for the latest articles, financial calculators and resources
Sources
(1) LIMRA, 2025 Facts About Life Insurance, 2025.
(2) Boston University, More Americans Aged 25 to 44 Are Dying Younger: BU Research Helps Explain Why, February 5, 2025.
Suggested content for you in Life Insurance
-
Life Insurance Facts: Debunking the Myths
-
How Does Life Insurance Work?
-
Life Insurance Awareness Month
-
What to Look for in a Life Insurance Policy
-
How to Create a Will: A Step-by-Step Guide
-
5 Qualifying Life Events: Reasons to Update Life Insurance Coverage
-
Buying Life Insurance for Cancer Patients
-
5 Benefits of Life Insurance for Families
-
14 Important Life Insurance Terms – Explained
-
Can I Buy Life Insurance for My Parents?
Explore other topics
Medicare Parts & Plans
Medicare Supplement Plan G vs. Plan N: Which One’s Best for You?Traveling in Retirement
Top 5 Cities for Seniors to RetireStaying Fit
5 Exercises for a Cardio Workout At Home All Categories
 Medicare
 Retirement Planning
 Business Resources
 Life Insurance
 Financial Planning
 Health & Well-Being
 Travel & Living